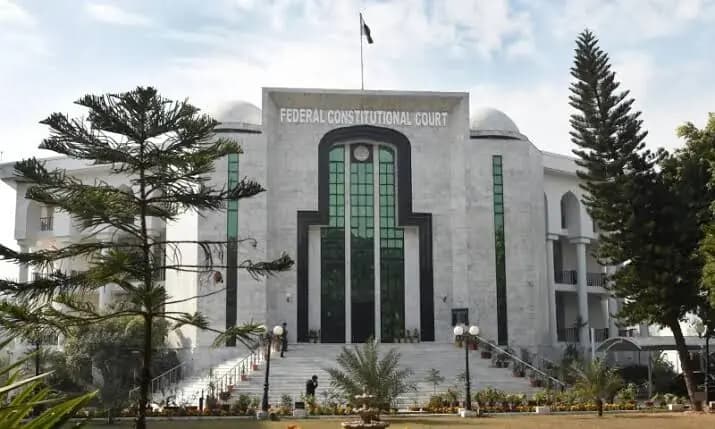

The Supreme Court of Pakistan decided on 30 October that a bank's taxable income under the Income Tax Ordinance, 2001, does not include pension fund surpluses unless those funds are returned to the employer.
Justice Aqeel Ahmed Abbasi authored the judgment which dismissed a civil appeal brought by the Commissioner Inland Revenue against MCB Bank. A three-member bench, including Justice Irfan Saadat Khan and Justice Shakeel Ahmed, affirmed the previous ruling issued by the Lahore High Court.
The Supreme Court observed that the Seventh Schedule contains no specific rules for surplus arising from pension funds. Instead, the court determined that Rule 9 of the Seventh Schedule directs the application of the Sixth Schedule's provisions.
Justice Aqeel Ahmed Abbasi stated that income earned on employer contributions to a pension fund only becomes taxable during the year the employer actually receives the amount back. The court clarified that the mere act of recording a surplus within financial statements does not transform it into taxable revenue.
The judges noted that tax liability cannot be determined by accounting principles alone, independent of the relevant tax legislation. Furthermore, the Supreme Court ruled that tax authorities are prohibited from rejecting a bank's consistent accounting practices without providing sound legal justification.