Key Takeaways
- HMRC ruled against John Griffin, the founder of Addison Lee, in a tax dispute.
- Griffin claimed he should be treated as a non-dom due to his Irish connections.
- The tribunal dismissed his claim, ordering him to pay £20.5m in back taxes.
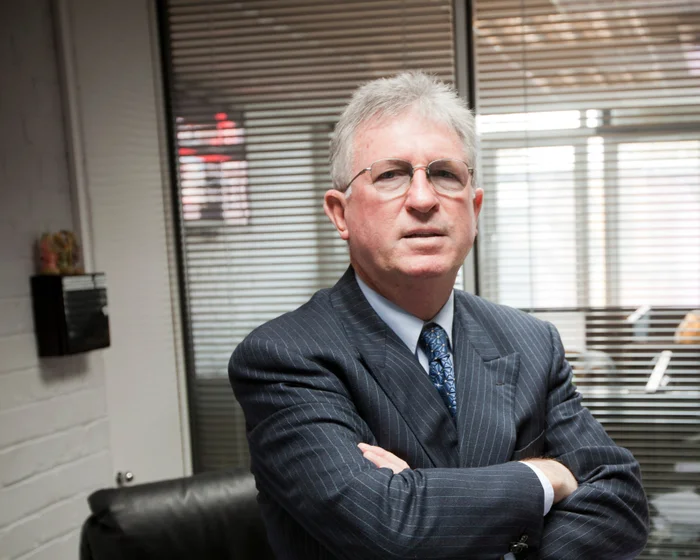
HM Revenue and Customs (HMRC) has won a legal battle against John Griffin, the founder of Addison Lee, who had argued he should be treated as a non-dom despite having lived in the UK since childhood.
In a ruling that has significant implications for tax law, the tribunal rejected Griffin’s claim, ordering him to pay £20.5m in back taxes.
Griffin had maintained his Irish connection, stating, “I was and am besotted with Ireland, infatuated with Ireland. I believe that I have always been and am Irish.”
However, the tribunal’s decision was based on Griffin’s long-term residency in the UK, which contradicted his claim of a primary connection to Ireland.
The ruling highlights the stringent criteria HMRC applies when assessing non-dom status, emphasizing the importance of residency and financial ties to the UK.
This case underscores the complexity of tax laws for individuals with dual or multiple connections, particularly in the context of business ownership and personal identity.
The outcome of this case could set a precedent for future legal challenges involving non-dom status and residency claims.
Griffin’s case serves as a reminder to business owners and individuals with complex tax situations to ensure their claims are thoroughly substantiated and aligned with the relevant legal standards.