Key Takeaways
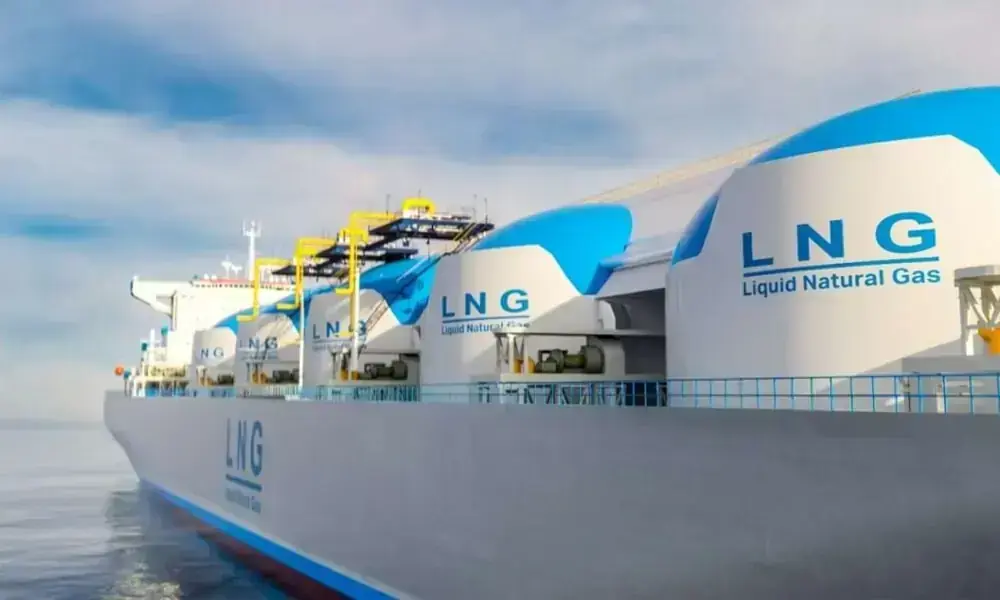
- RLNG imports from Qatar have been reduced due to force majeure, providing a temporary cushion to Pakistan’s economy.
- The current account posted a marginal surplus of $49 million despite higher oil prices, compared to $586 million in the same period last year.
- Lower RLNG imports have saved the country $1.5 billion, reducing the import bill and load-shedding in Punjab.
Pakistan’s economy has seen a temporary reprieve from the international oil price crisis, thanks to reduced liquefied natural gas (RLNG) imports from Qatar. This reduction, due to force majeure, has provided a cushion against the impact of higher oil prices, which have surged by 43 percent since the same period last year.
According to the central bank’s data, the current account posted a marginal surplus of $49 million from March to August 2026, compared to a surplus of $586 million in the same period of 2025. This indicates that despite the rise in oil prices, the country’s economic performance has been relatively stable.
The reduction in RLNG imports has also had a positive impact on the import bill. While goods imports increased by 9 percent year-on-year (YoY) to $34.3 billion, the bill has been kept in check. The lower supply has resulted in a lower import bill, saving the country approximately $1.5 billion. This has translated into fewer load-shedding hours in Punjab during the peak summer months, with only two to three hours of power cuts reported.
However, the rise in petroleum imports by 19 percent to $1.5 billion is a concern. Despite the higher bill, it is still 25 percent lower than during the 2022 crisis. This is partly due to the passing on of higher oil prices to consumers and a decline in diesel demand in agriculture and backup power generation, thanks to the widespread adoption of solar and other renewable energy sources over the past four years.
The central bank’s data also shows that the trade deficit has been well cushioned by growth in home remittances and services exports. This has kept the current account comfortable, despite the increase in petroleum imports. However, the stagnation in goods exports remains a worry, with no new sectors emerging as stars. The government has had to provide fiscal and monetary incentives to boost exports, but without these crutches, the sector is failing to grow.
The medium- to long-term concern is a possible slowdown in economic growth due to the aftermath of the Gulf crisis. The reduction in RLNG imports, while providing temporary relief, may not be sustainable. The government will need to focus on diversifying energy sources and supporting export growth to ensure long-term economic stability.
In conclusion, while the current situation offers a temporary reprieve, the economy faces ongoing challenges that require careful management. The government’s focus on diversifying energy sources and supporting export growth will be crucial in navigating the post-crisis landscape.