Key Takeaways
- Lahore High Court sets aside orders of Federal Tax Ombudsman and president.
- Case concerns delayed adjudication of seized cigarettes.
- Court rules FTO cannot assume jurisdiction of statutory appellate forums.
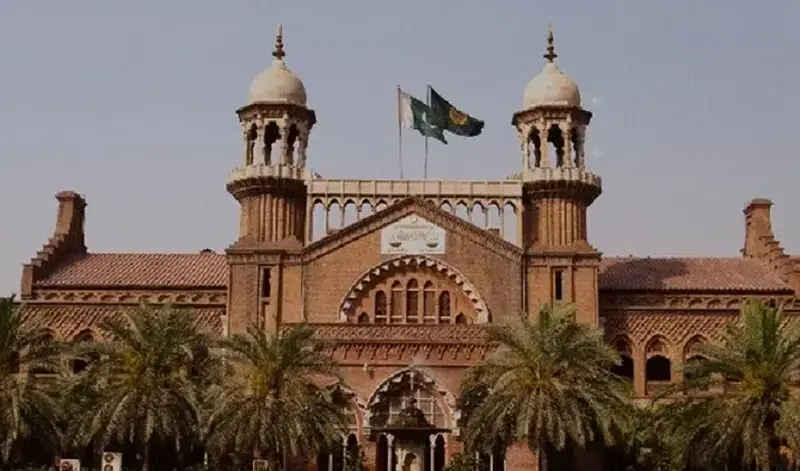
The Lahore High Court has ruled that the Federal Tax Ombudsman (FTO) and the president have no jurisdiction to entertain a complaint about delayed adjudication of seized goods, as the matter falls within the domain of statutory tax authorities and appellate forums.
The decision was made in a case where the Commissioner Inland Revenue, Multan Zone, filed a petition against a private cigarette dealer, the FTO, and the President’s Secretariat.
According to the case details, the Directorate of Intelligence and Investigation (Inland Revenue), Multan, obtained a search warrant and recovered 641 cartons of allegedly illicit, non-duty-paid, and counterfeit cigarettes from the dealer’s premises.
The dealer’s representative could not produce invoices or records proving duty payment, leading to a show-cause notice being issued.
Instead of responding to the notice, the dealer filed a complaint with the FTO under Section 10(1) of the Federal Tax Ombudsman Ordinance, 2000, alleging that the tax department had unduly delayed adjudicating the seized goods, causing him financial losses.
The FTO entertained the complaint and directed that adjudication proceed before the appropriate forum. The tax department’s representation against this order was subsequently dismissed by the president, prompting the department to approach the Lahore High Court.
Justice Jawad Hassan, the author of the judgement, held that jurisdiction ‘goes to the root of the matter,’ and that an order passed without lawful authority is void from the outset.
Examining Section 9 of the FTO Ordinance, the bench observed that while the ombudsman is empowered to investigate allegations of maladministration by the Revenue Division or its employees, that power is not absolute.
The bench noted that Section 9(2)(b) expressly bars the FTO from inquiring into matters relating to assessment of income or wealth, determination of tax or duty liability, or classification and valuation of goods, wherever the law already provides a remedy of appeal, review, or revision.
The bench held that the FTO’s role is to provide an independent, expeditious remedy against maladministration, ‘without allowing the FTO to assume the jurisdiction of statutory appellate or adjudicatory forums.’